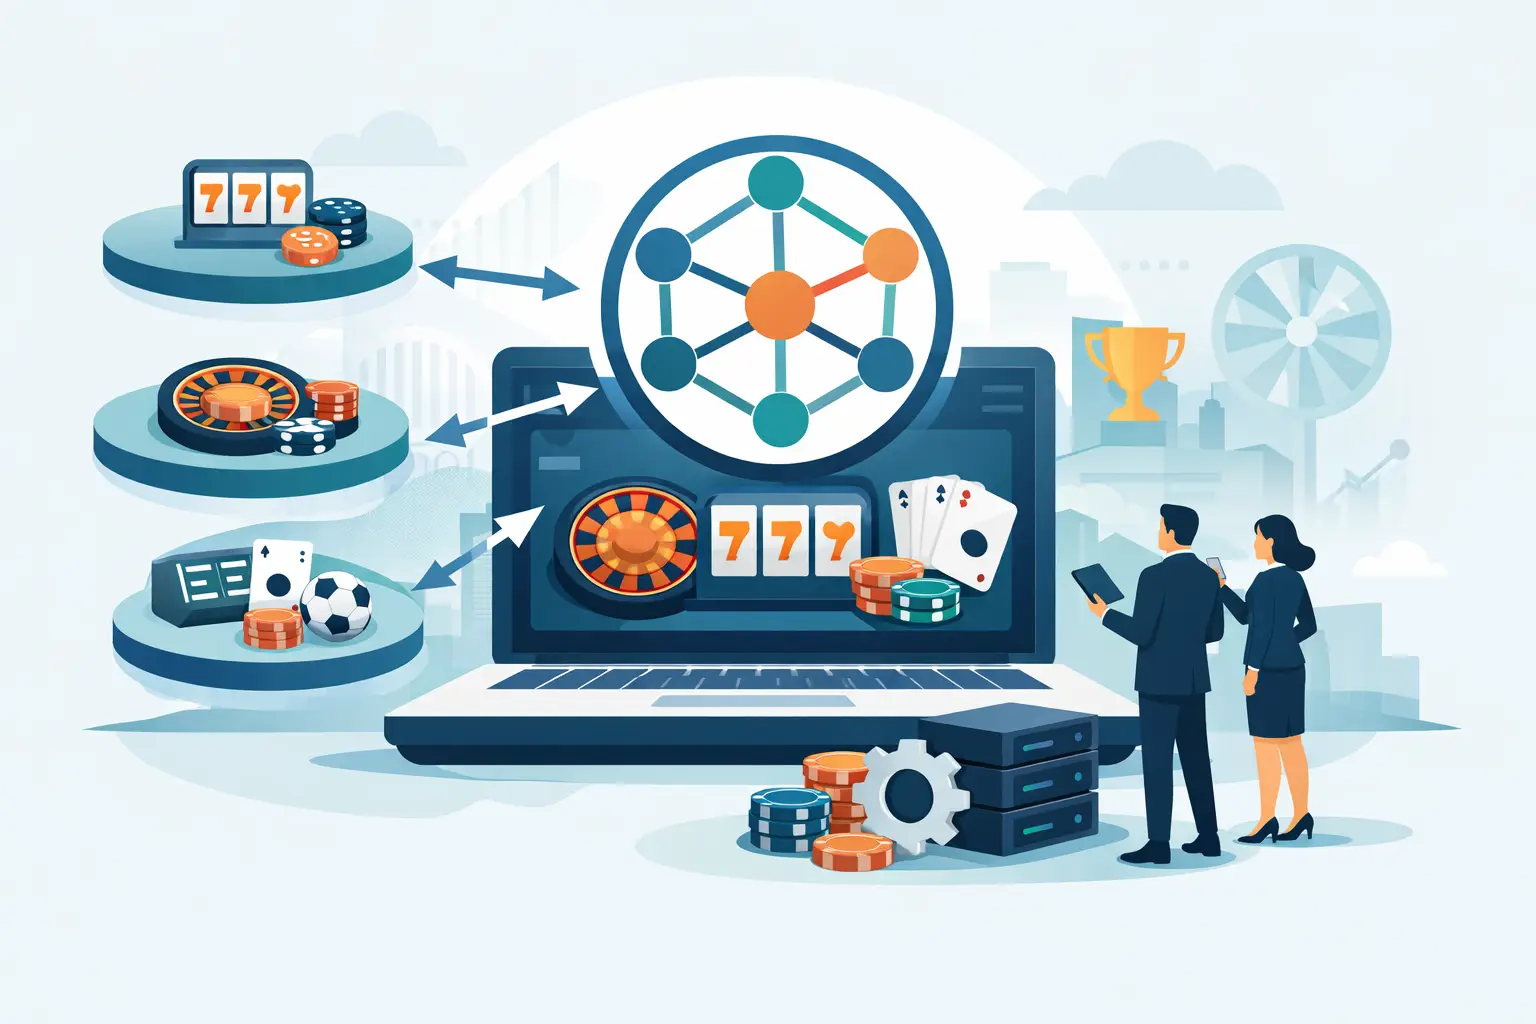
When an iGaming operation relies on one vendor for content, another for payments, a third for KYC, and several more for CRM, wallet logic, reporting, and back-office controls, growth starts to look expensive. Every additional integration adds latency, support overhead, compliance complexity, and another point of failure. That is exactly why a vendor consolidation strategy has become a serious operational priority for operators that want faster launches, tighter control, and fewer technical compromises.
For many gaming businesses, fragmentation does not begin as a mistake. It often starts as a practical response to speed. A startup launches with the fastest sportsbook feed available, then adds a separate casino aggregator, then patches in a payment service optimized for one geography, then introduces standalone retention tools because the original stack could not support segmentation at scale. On paper, each decision makes sense. Over time, the architecture becomes harder to govern.
The result is not just vendor sprawl. It is a business model that absorbs friction at every layer. Product teams wait on multiple roadmaps. Finance teams reconcile data across disconnected systems. Operations teams manage overlapping support relationships. Compliance teams inherit inconsistent reporting structures. Engineering teams become integration managers instead of platform builders.
Why vendor consolidation strategy matters in iGaming
In most digital businesses, too many vendors create inefficiency. In iGaming, they also create revenue risk. Platform performance affects conversion. Payment instability affects deposits. Weak synchronization between wallet, player account, and content systems affects trust. Delays in reporting or data consistency affect licensing, auditing, and decision-making.
A strong vendor consolidation strategy reduces that exposure by simplifying the stack around a smaller number of infrastructure partners. This does not mean forcing every capability into a single box regardless of fit. It means identifying where consolidation improves control, speed, economics, and accountability without reducing competitiveness.
For operators entering regulated markets, consolidation often improves readiness. Fewer integration points mean fewer certification dependencies and fewer moving parts to review before launch. For established brands, it can improve margin by reducing duplicated fees, overlapping support contracts, and unnecessary maintenance work. For enterprise groups managing multiple brands, consolidation can create a repeatable operating model across regions, products, and teams.
The commercial upside is clear. If your teams spend less time coordinating vendors, they spend more time optimizing acquisition, retention, and market expansion.
The hidden cost of fragmented vendor stacks
The obvious cost of fragmentation is financial. Multiple contracts, setup fees, revenue shares, and support retainers add up quickly. But the larger cost is operational drag.
Consider what happens when a player deposit fails. If payments, wallet infrastructure, identity checks, and fraud controls sit with different providers, your team may need multiple support channels to identify the source of the issue. Resolution slows down. The player experience degrades. Internal accountability gets blurred because no single partner owns the full transaction path.
The same pattern appears in content deployment. If your casino aggregation layer is separate from player account management and bonus logic, introducing a new game provider may require manual work across several systems. Promotions can become difficult to standardize. Reporting can vary by source. Product velocity drops.
Fragmentation also weakens strategic visibility. Operators need one coherent view of player behavior, payment performance, lifetime value, and content engagement. If data is spread across disconnected systems with inconsistent schemas, leadership gets reports, but not clarity. That difference matters when expansion decisions depend on accurate operating intelligence.
What a good vendor consolidation strategy actually looks like
A good strategy is not a rushed vendor reduction exercise. It is a deliberate architecture and procurement decision tied to business objectives.
First, it starts with defining where consolidation matters most. For one operator, the highest priority may be content aggregation and wallet unification. For another, it may be replacing regional payment patchwork with a centralized payment gateway that still supports local methods. For a white-label business, the biggest gain may come from bringing player management, back office, reporting, and compliance workflows under one platform layer.
Second, it evaluates vendors by system depth, not feature count alone. A provider may claim broad coverage, but if the integrations are shallow, support is fragmented, or reporting is inconsistent, consolidation will not deliver the expected value. Serious buyers should examine API maturity, uptime history, certification readiness, scaling performance, data model consistency, and operational support.
Third, it accounts for lock-in risk. Consolidation should improve leverage, not remove it. That usually means choosing partners with modular architecture, strong API access, transparent data portability, and a roadmap that aligns with the operator’s growth plan. A consolidated stack should still give the business options.
Where consolidation creates the biggest gains
In iGaming, three layers typically produce the strongest return when consolidated.
The first is platform infrastructure. When player accounts, wallet logic, back-office controls, bonus systems, and reporting sit within one architecture, operators gain cleaner workflows and more reliable data. That improves daily operations and shortens the path from product idea to market execution.
The second is content delivery. A unified aggregation model with a single API reduces integration management and expands content access without multiplying technical effort. It also makes it easier to maintain consistency across localization, campaign rules, and content rollout.
The third is payments. This is often where fragmentation becomes most expensive. Regional payment methods, fraud controls, crypto capability, reconciliation, and payout flows can become a patchwork if added one by one. Consolidating payment infrastructure under a secure, scalable framework gives operators better performance and stronger operational control, especially across multiple jurisdictions.
When not to consolidate everything
There is a limit to consolidation. Not every function should be handed to one provider.
If a specific market requires a niche payment method with proven local conversion advantages, keeping a specialist vendor may be the right move. If a proprietary CRM or advanced odds engine creates measurable differentiation, replacing it for the sake of simplification may hurt the business more than it helps.
This is where mature strategy matters. The goal is not minimal vendor count at any cost. The goal is a stack that is simpler where simplicity creates leverage and specialized where specialization creates revenue. That balance will vary by operator size, geography, licensing model, and product ambition.
How to execute a vendor consolidation strategy without disruption
Most consolidation programs fail when they are treated as procurement projects instead of operating model changes. The cleaner approach starts with a full dependency map. Identify every vendor by function, cost, contract structure, integration complexity, business criticality, and data ownership. Then rank each relationship by strategic value.
From there, build the target architecture. Decide which capabilities should live inside a unified platform, which should remain modular, and which can be retired altogether. This step requires product, operations, finance, compliance, and technical stakeholders in the same room. Consolidation decisions made in silos usually create new bottlenecks.
Migration sequencing is the next critical piece. High-risk systems such as wallet, payments, and player management need careful transition planning. Content and reporting layers may be easier to phase. The right sequence depends on your contracts, traffic profile, and market commitments.
The strongest partners make this process easier by supporting phased deployment rather than forcing a single hard cutover. In practice, operators need room to test data integrity, validate performance, and protect player experience before fully switching core systems.
For businesses that want to scale without rebuilding around every new market or product line, this is where an all-in-one infrastructure partner becomes commercially attractive. A provider such as Gameifylabs can reduce vendor complexity across platform, aggregation, payments, and back-office operations while still giving operators the speed and technical control required for serious growth.
Measuring whether consolidation is working
A vendor consolidation strategy should show results in operating metrics, not just in cleaner org charts.
Launch timelines should get shorter. Incident resolution should improve because fewer handoffs are involved. Reporting should become more consistent. Payment performance should stabilize. Engineering resources should shift from maintenance-heavy integrations toward product improvements that affect acquisition and retention.
Commercial metrics matter too. Watch total vendor spend, support overhead, margin leakage from duplicated services, and the time required to activate new geographies or content verticals. If consolidation is effective, the business should not only look simpler. It should move faster.
There is also a governance benefit that becomes more visible over time. Fewer critical vendors means clearer accountability, stronger service management, and better executive oversight. In a sector where uptime, compliance, and trust directly affect revenue, that control is not a nice-to-have. It is part of the growth model.
The operators that scale cleanly are usually not the ones with the longest vendor list. They are the ones that know which capabilities to centralize, which to keep specialized, and how to align infrastructure decisions with commercial goals. If your stack is slowing down launches, complicating compliance, or stretching support teams thin, that is usually the moment a vendor consolidation strategy stops being an efficiency project and starts becoming a competitive one.
DiscussionHave a technical perspective or question?Open discussion