A failed deposit is not just a declined transaction. For an iGaming operator, it can mean a lost first-time depositor, an abandoned sportsbook bet before kickoff, or a high-value casino player moving to a competitor. A practical payment routing optimization example shows how to turn payment orchestration from a basic gateway connection into a measurable revenue and risk-control function.
The objective is not to send every transaction to the provider with the lowest listed fee. It is to select the route most likely to authorize the payment at an acceptable cost, while meeting local regulations, fraud controls, processing capacity, and player experience requirements. That decision must happen in milliseconds, backed by clear rules and continuous performance data.
What payment routing optimization means in iGaming
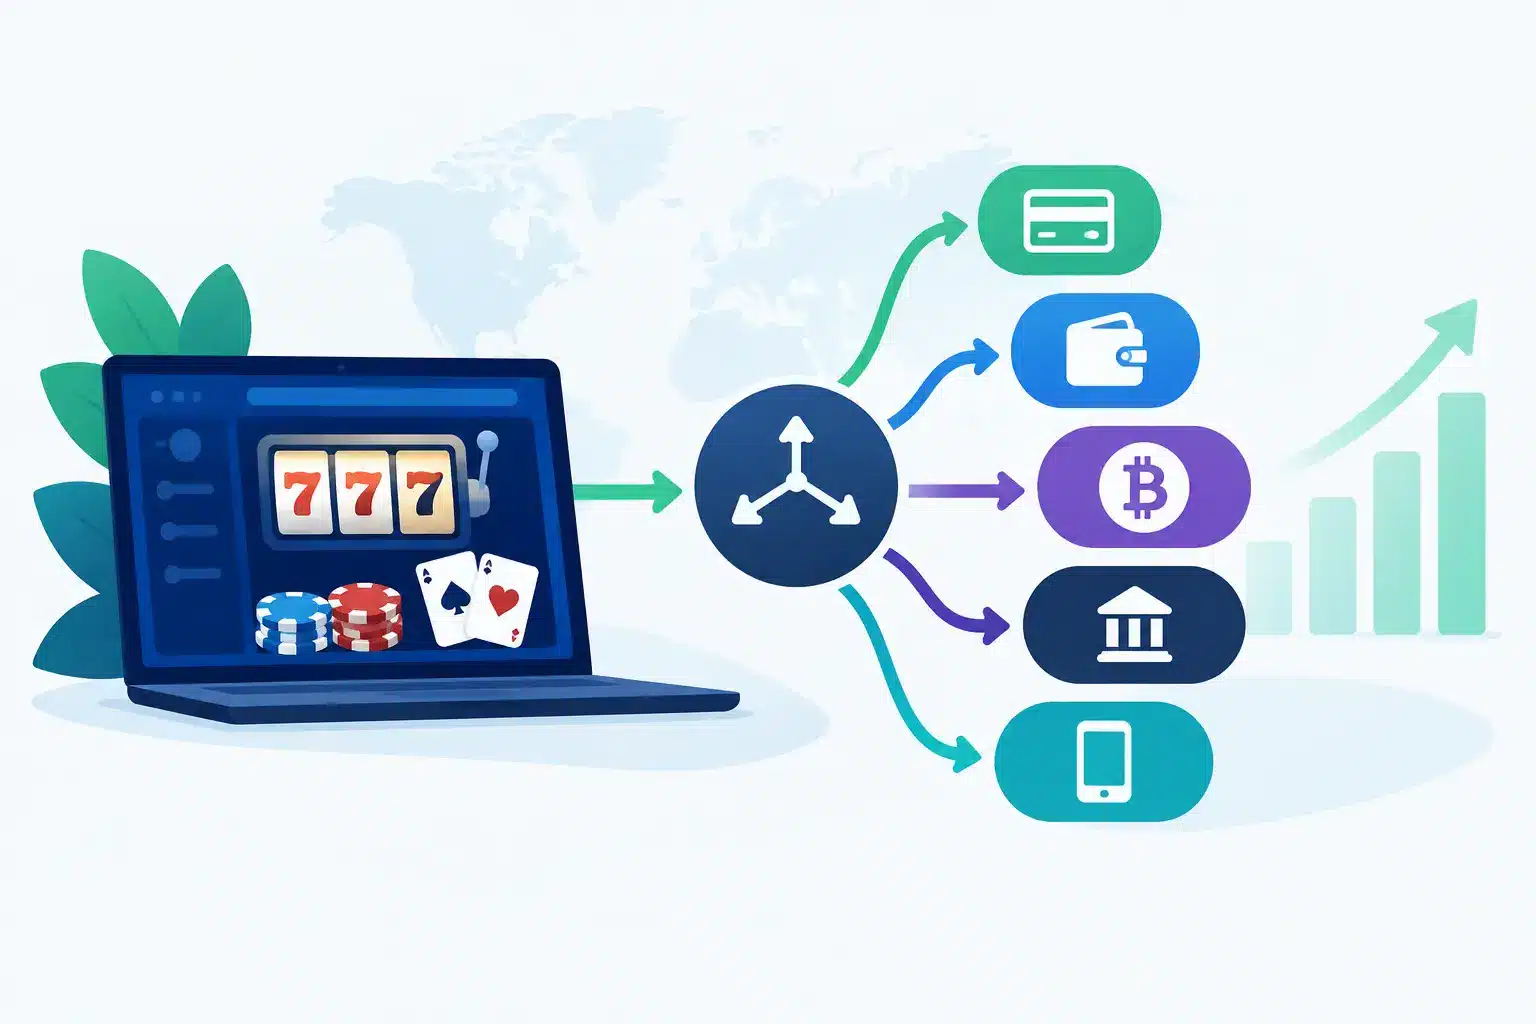
Payment routing optimization is the logic that determines which payment service provider, acquirer, local payment method, or fallback path should process a transaction. The routing engine evaluates transaction attributes, applies business and risk rules, and directs the request to the most suitable available payment rail.
For online casino and sportsbook operations, those attributes commonly include player country, currency, payment method, issuer region, transaction value, device signals, player status, time of day, and previous authorization outcomes. The resulting decision can differ materially between a $20 first deposit from a new player and a $2,000 withdrawal request from a verified VIP.
A single processor can be enough for a narrow market with one currency and a stable payment mix. It becomes a constraint as an operator expands. Approval rates vary by issuer and geography. Acquirers have different strengths by card scheme and market. Alternative payment methods can outperform cards in specific jurisdictions. A routing strategy provides control over those variables without forcing the operations team to manage disconnected integrations.
Payment routing optimization example: a cross-border deposit
Consider an operator licensed to serve several regulated markets. A player in Brazil attempts a first deposit of BRL 250 using a locally issued Visa card. The platform supports two card acquirers, a local instant-payment provider, and an alternative payment service provider.
A basic setup sends the deposit to Acquirer A because it is the default processor. Acquirer A has competitive pricing, but its authorization rate for Brazilian-issued cards has fallen to 68% during evening peak hours. A decline may be caused by issuer preferences, insufficient issuer recognition of the merchant, velocity rules, or an avoidable technical mismatch. The player sees a generic decline message and may not try again.
An optimized routing configuration makes a different decision. It first validates the player session, KYC status, deposit limit, device risk score, and card eligibility. If the transaction passes these controls, the routing layer recognizes the Brazilian issuer, BRL currency, first-deposit status, and current performance pattern. It sends the authorization to Acquirer B, which is configured as the preferred route for this issuer segment because its rolling approval rate is 82%.
If Acquirer B returns a soft decline, such as a temporary issuer response or a request for stronger authentication, the system can present an approved fallback rather than blindly retrying the same path. For example, it may guide the player to the local instant-payment method, subject to local rules and the operator’s UX design. If the card transaction receives a hard decline, such as an invalid account response, the platform should not continue retries that create unnecessary fees, fraud exposure, or player frustration.
The result is not simply a higher approval rate. It is a more intentional deposit journey: the player receives an appropriate payment option, the operator avoids wasteful routing, and the payment team can explain why the decision was made.
The routing decision in practice
A production rule might prioritize Acquirer B when the player is in Brazil, the card is locally issued, the amount is below a configured threshold, and the provider’s real-time health status is normal. Acquirer A remains available for issuer ranges where it performs better or when Acquirer B reaches capacity limits.
The rule should also recognize exceptions. A high-risk device signal may require a different flow, additional verification, or a transaction block. A high-value deposit may need a route with stronger monitoring and a lower chargeback profile, even if its authorization rate is marginally lower. Optimization is a balance between conversion, cost, fraud, compliance, and operational resilience.
Build routing logic around measurable signals
Routing rules should begin with data that can be observed and audited. The most valuable signal is not always a provider’s aggregate approval rate. An 80% global approval rate can conceal poor performance for one country, issuer category, or transaction type.
Segment performance by market, currency, payment method, BIN or issuer range where permitted, transaction amount, player lifecycle stage, and time window. Compare authorization rate, completed deposit rate, latency, technical error rate, refund performance, dispute rate, and effective processing cost. Effective cost includes failed-transaction fees, chargeback exposure, operational effort, and lost conversion, not only the published processing percentage.
Provider health also needs real-time attention. A route that was preferred yesterday may be producing elevated timeouts now. Your platform should monitor response codes, latency, error concentration, and processor availability. When a defined threshold is breached, routing can shift traffic to an approved secondary provider until service quality returns to normal.
This requires restraint. Moving all traffic after a small, temporary variance can create instability and make performance analysis harder. Use minimum data thresholds, short and long monitoring windows, and capacity guardrails. The best routing policies are adaptive without becoming unpredictable.
Separate smart retries from unnecessary retries
Retries are often mishandled as a simple conversion lever. Repeating a transaction through multiple processors can help when the decline is route-specific or temporary. It can also increase issuer suspicion, trigger duplicate-payment concerns, and create additional costs.
Classify responses before deciding what happens next. Technical failures, processor timeouts, and certain soft declines may qualify for a controlled retry or fallback route. Hard declines, suspected fraud responses, account closures, and regulatory blocks should stop the flow. The exact response-code treatment depends on payment method, acquiring partner guidance, and market requirements.
Set retry limits at the player and transaction level. Preserve idempotency controls so a timeout does not become two captured deposits. Make sure the back office gives payment operations teams a complete transaction trail, including the first route, response code, fallback action, final state, and any manual intervention.
Design for local payment preference, not card-only coverage
Card acquiring remains central to many iGaming payment stacks, but local payment behavior should shape routing strategy. In some markets, bank transfer, instant account-to-account payments, digital wallets, vouchers, or cash-based methods may provide stronger conversion and greater player familiarity than international card flows.
This does not mean presenting every available method to every player. Excess choice can reduce completion. Instead, use location, currency, verified player history, and payment success data to place the most relevant methods first. A player who repeatedly funds through a local method should not need to search past unfamiliar options on each visit.
Withdrawal routing deserves equal attention. Deposits can be optimized for speed and authorization, while withdrawals must account for closed-loop requirements, anti-money laundering controls, payment-method eligibility, payout cost, and expected settlement time. The ideal payout route is often the method that returns funds safely to a verified source, not simply the fastest rail.
Governance makes optimization sustainable
Payment routing touches regulated workflows, player funds, fraud controls, and financial reconciliation. Rules should therefore be owned jointly by payments, risk, compliance, product, and engineering teams. Changes need version control, approval paths, testing procedures, and rollback capability.
Before releasing a new routing policy, test it against historical transaction patterns and introduce it to a limited traffic segment. Monitor approval uplift alongside fraud rate, dispute rate, deposit completion, latency, and support contacts. A higher authorization rate is not a win if it materially increases fraud losses or creates reconciliation failures.
A unified payment layer reduces the operational burden by centralizing provider integrations, routing logic, transaction monitoring, and back-office visibility. For operators building across markets, infrastructure partners such as Gameifylabs can help consolidate these capabilities into a payment architecture that is designed for scale rather than patched together market by market.
Payment routing should be treated as a living operational system. Review performance by market and payment method regularly, keep fallback options tested, and let verified transaction data determine where each player payment should go next.
DiscussionHave a technical perspective or question?Open discussion