Every additional vendor in an iGaming stack adds one more dependency that can slow a launch, complicate compliance, or create friction in daily operations. That is the real reason why operators need vendor consolidation. It is not just a procurement decision. It is an infrastructure strategy that affects speed to market, platform stability, reporting accuracy, and the ability to scale without accumulating operational drag.
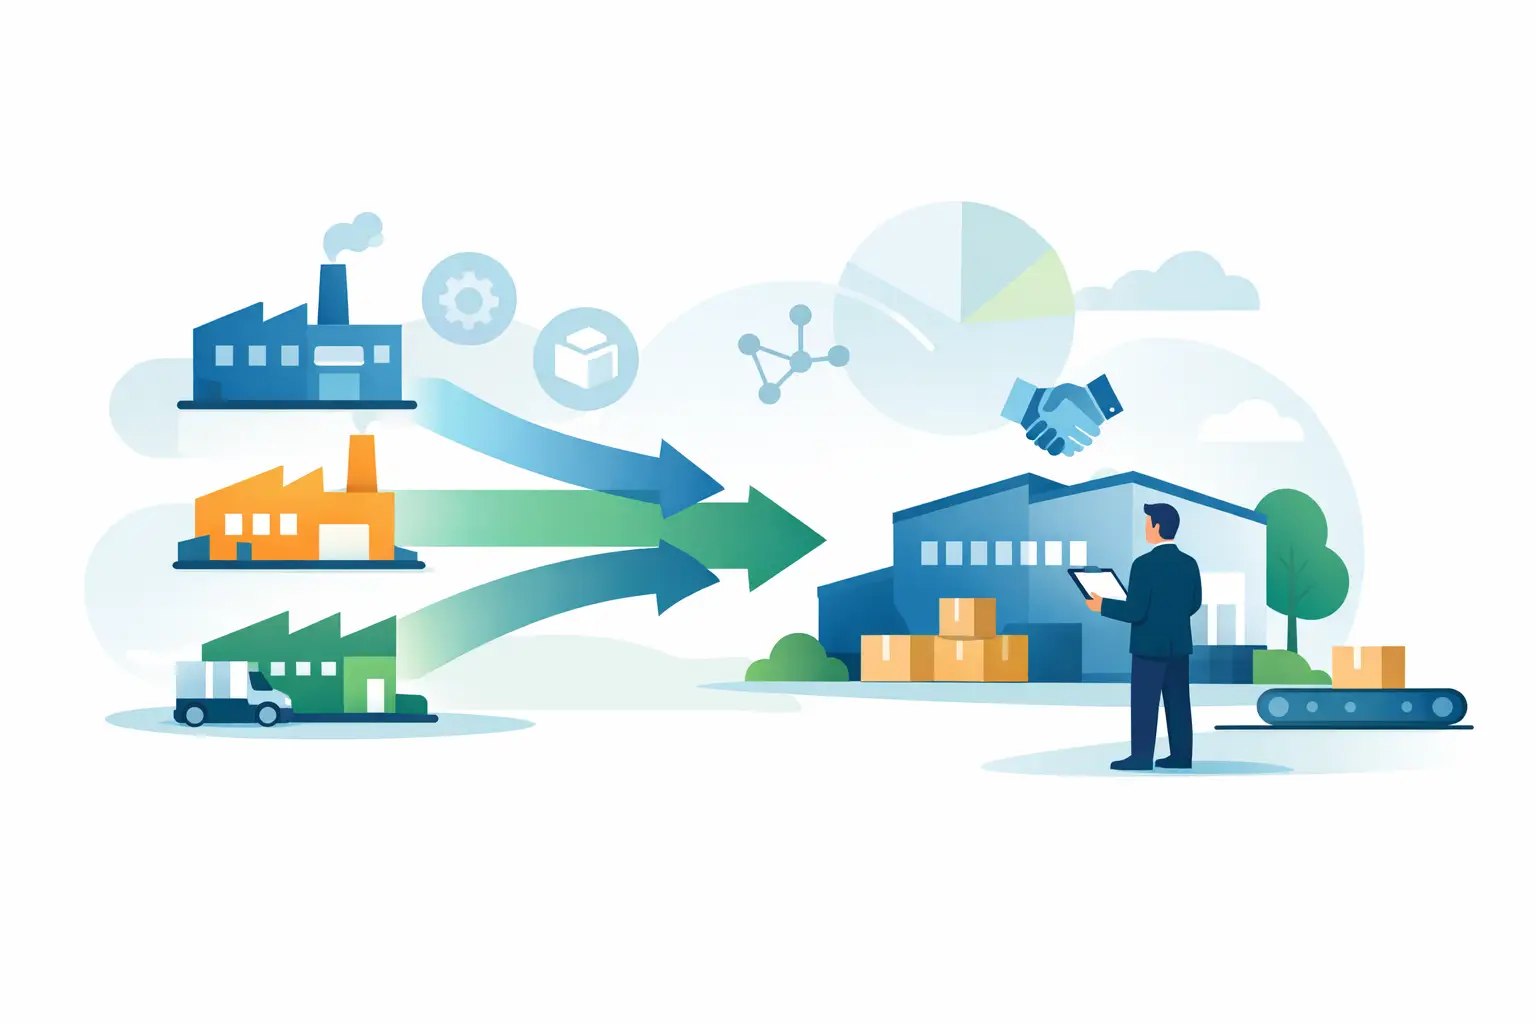
For operators entering new markets or expanding an existing casino or sportsbook, fragmented architecture often looks manageable at first. One provider supplies content, another handles payments, a third manages CRM, and a fourth owns the wallet or player account environment. On paper, that can appear flexible. In practice, it often creates handoff failures, duplicated costs, and long resolution times when something breaks.
Why operators need vendor consolidation in real operations
The strongest argument for consolidation is not convenience. It is control.
When multiple vendors own core parts of the player journey, operators lose visibility into where performance issues start and where accountability ends. A deposit delay may involve the payment gateway, fraud rules, wallet logic, and back-office permissions. A missing game launch can involve content aggregation, front-end rendering, geo-rules, and session management. In a fragmented environment, every issue becomes a multi-party discussion.
That model does not scale well. As operator volume grows, the cost of coordination grows with it. Technical teams spend more time managing vendor dependencies. Operations teams work around reporting mismatches. Product teams wait longer to release features because each change has to pass through several systems with different logic and release cycles.
Vendor consolidation reduces that friction by narrowing the number of moving parts. Fewer integrations mean fewer failure points. Shared architecture means more predictable behavior across payments, player management, content delivery, and reporting. For leadership teams, that translates into tighter execution and clearer ownership.
Speed to market is usually the first pressure point
Most operators do not start thinking seriously about consolidation because of architecture theory. They do it because launches take too long.
A fragmented stack often delays deployment in ways that are easy to underestimate. Each vendor has its own technical documentation, onboarding timeline, testing process, escalation path, and certification constraints. Even when each component works well on its own, stitching them together into one production-ready environment takes time.
That delay is expensive. In regulated markets, timing can determine whether a brand captures early demand or arrives after stronger competitors have already acquired players. In emerging markets, speed matters because payment methods, local preferences, and promotional strategies need to be tested quickly.
A consolidated model shortens the path from agreement to go-live. When content, payments, wallet infrastructure, back-office tools, and user management are designed to operate within the same framework, implementation becomes more predictable. Operators can spend less time coordinating vendors and more time refining the product they are actually bringing to market.
This does not mean every operator should force everything into one monolithic system. If a business has a specialized requirement for a certain market or vertical, selective external integrations may still make sense. But the closer the core stack is to a unified environment, the faster teams can deploy and iterate.
Consolidation reduces operational risk, not just admin work
The hidden cost of vendor sprawl is risk distribution without clear control.
In iGaming, operators are responsible for much more than uptime. They have to manage KYC flows, transaction security, fraud controls, player data handling, reporting consistency, localization, and jurisdiction-specific requirements. The more disconnected the systems are, the harder it becomes to maintain a clean operational posture.
For example, if one vendor manages account data, another processes deposits, and another controls game session records, data reconciliation becomes a recurring risk area. Even small mismatches can create larger problems in finance, support, and compliance. A player may see one balance on the front end, support may see another in a back-office tool, and payment records may reflect a third state because systems sync on different schedules.
Vendor consolidation helps contain that complexity. Shared infrastructure makes data movement more consistent and reduces the number of translation layers between systems. It also improves incident response. When a smaller number of partners own more of the stack, investigations move faster because fewer boundaries have to be crossed before root cause analysis can begin.
This is especially relevant for operators growing across regions. Expansion tends to expose weak architecture quickly. More currencies, more payment methods, more regulatory rules, and more player segments all increase strain. A fragmented stack can support that for a while, but usually with rising overhead and declining agility.
Why operators need vendor consolidation for cleaner reporting
Decision-making gets worse when reporting is split across systems that were never designed to speak the same language.
Operators rely on accurate data to optimize acquisition, retention, payments, risk, and content performance. But if one vendor reports net gaming revenue one way, another tracks bonus cost differently, and a third delays transaction updates, leadership ends up working from partial truth. Teams may spend hours reconciling dashboards before they can act on what the business is actually showing.
Consolidation improves reporting because the data model is more aligned from the start. When player behavior, transaction activity, game performance, and account status are captured across connected systems, operators can trust the numbers sooner. That makes pricing decisions faster, promotional changes safer, and market-level comparisons more useful.
This matters at the executive level, but it matters just as much on the floor. Customer support teams need a reliable player view. Finance teams need transaction clarity. Product teams need feature-level insight. Marketing teams need campaign attribution they can actually use. Cleaner infrastructure creates cleaner reporting, and cleaner reporting improves execution.
The trade-off: flexibility versus complexity
There is a reason some operators resist consolidation. They do not want to lose flexibility.
That concern is valid. A fully consolidated environment can become restrictive if the provider lacks strong coverage, modern APIs, or the ability to support custom workflows. Operators with advanced in-house capabilities may prefer best-of-breed tools in certain areas, especially if they operate at large scale or have unique product requirements.
The question is not whether flexibility matters. It does. The question is whether the flexibility is producing competitive advantage or simply creating maintenance burden.
If an operator is managing six or eight critical vendors just to preserve optionality, but each change request requires cross-vendor coordination and each incident involves finger-pointing, that is not strategic flexibility. It is operational inefficiency.
The strongest consolidation models preserve room for customization while standardizing the foundation. That means unified APIs, centralized back-office controls, stable wallet and payment architecture, and broad content access inside one operational framework. Operators still retain the ability to shape brand, front-end experience, and market strategy without rebuilding the infrastructure layer every time they grow.
Consolidation supports better commercial outcomes
Infrastructure choices show up in revenue faster than many teams expect.
If deposits fail too often, conversion drops. If support cannot resolve account issues quickly, churn rises. If launching a new market takes six extra months because systems need custom stitching, growth slows. If finance teams cannot reconcile numbers efficiently, margin visibility weakens.
Vendor consolidation improves these outcomes by reducing latency across the business. Payments are easier to manage when gateway logic, wallet behavior, and reporting are aligned. Content operations improve when a single integration opens access to a broader supplier base. Platform updates move faster when fewer systems need bespoke adaptations.
That is why consolidation is not just a technical upgrade. It is a commercial advantage. It helps operators protect uptime, reduce escalation time, improve internal efficiency, and bring new offers to market with less friction.
For many brands, the right approach is not to keep adding vendors every time a new requirement appears. It is to strengthen the underlying operating model so the business can scale from a more stable core. That is where providers built around unified infrastructure, such as Gameifylabs, become strategically relevant.
The operators that scale well are rarely the ones with the most vendors. They are the ones with the clearest architecture, the fastest decision paths, and the fewest points of avoidable failure. If your stack is making growth harder instead of easier, consolidation is not a future consideration. It is a present operating decision.
DiscussionHave a technical perspective or question?Open discussion